Aplicación móvil
DESCARGAR DESDE APPLE STORE O GOOGLE PLAY

Mantenimiento de Banca Digital
¡Atención! Este fin de semana haremos un pequeño mantenimiento para que todo siga funcionando de la mejor manera.
Banca Digital, incluyendo Zelle®, podría no estar disponible la noche del sábado 20 de septiembre, entre las 10 p.m. y las 4 a.m. de la mañana siguiente.
Los cajeros automáticos ATM de la red Rize podrían no estar disponibles temporalmente el 8 de septiembre, de 7 a 10 p.m.
Recordatorio importante: NUNCA lo llamaremos, le enviaremos un correo electrónico ni un mensaje de texto para pedirle su contraseña. Su contraseña es privada, ¡manténgala segura! Obtenga más información y actualizaciones mensuales sobre nuestra página de prevención de fraude.
Mantenimiento de Banca Digital: sábado 20 de septiembre, de 10 p.m. a 4 a.m. Más información.
CARD MANAGEMENT
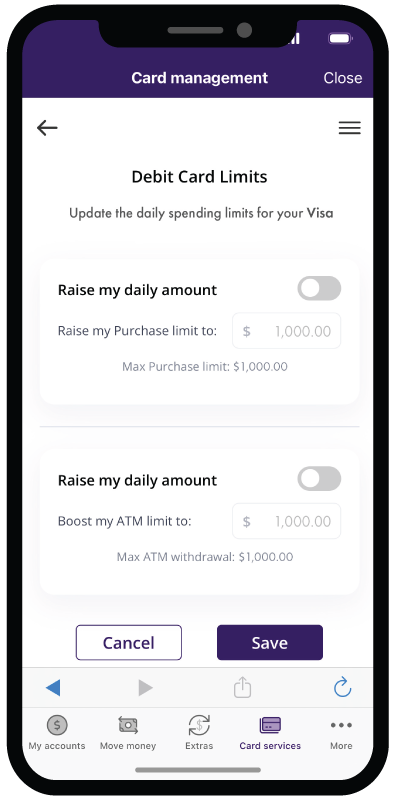
Boost it in seconds
1.
Temporarily boost your debit limit when you need.
2.
Have more flexibility for those bigger purchases.
3.
No calls.
No wait.
No hassle.
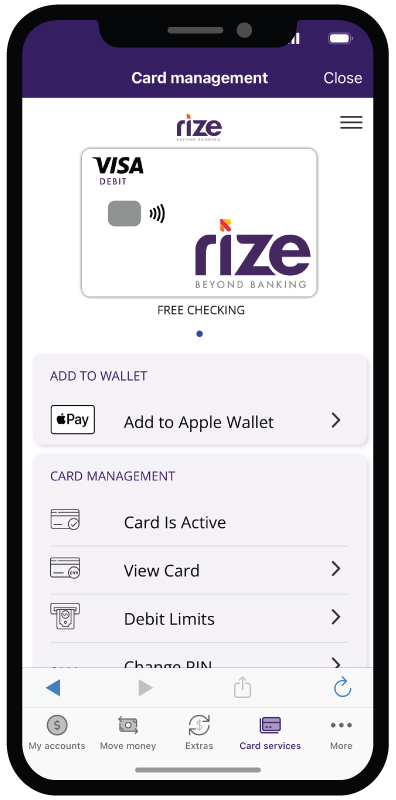
Adjust debit limits in card management
Keep your card secure
Change your PIN in card management
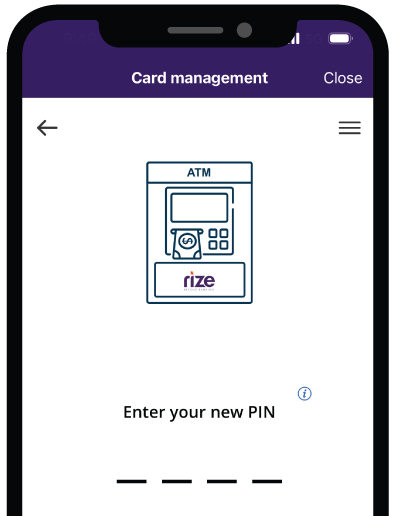
You can update your PIN anytime, anywhere in digital banking.
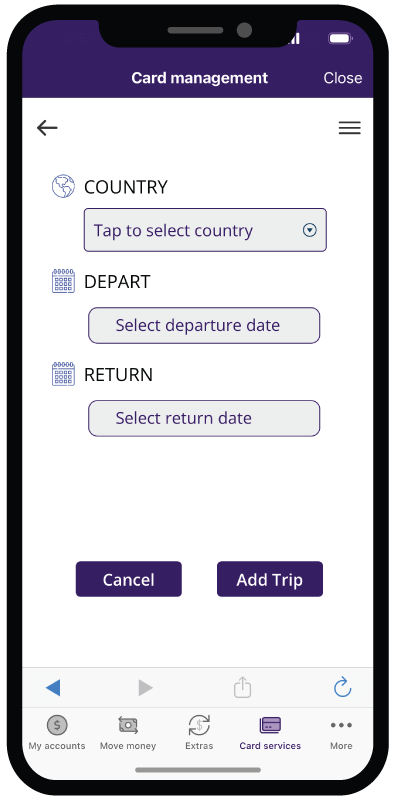
Plan ahead swipe anywhere
Traveling soon? Add your dates and keep your card working wherever you land – set up to five trips at a time.
Set travel notifications in card management
Take control in a tap
1.
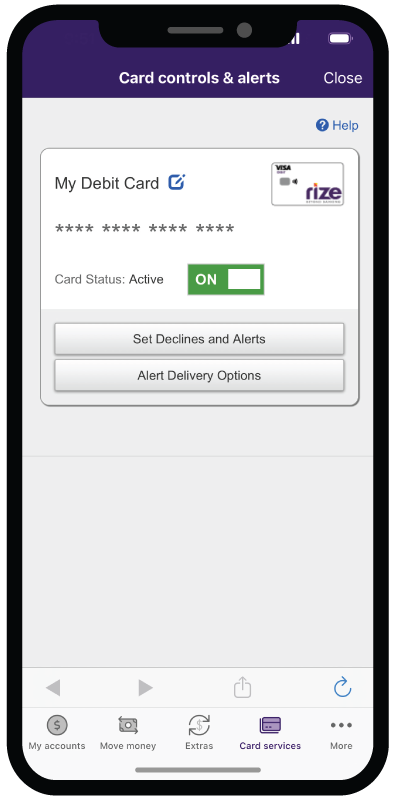
Turn your card off instantly if it’s lost or misplaced.
2.
Turn it back on anytime it’s back in your hands.
3.
Control everything right from your phone in seconds.
Turn your cards on, off, and back on again in card controls
Real-time peace of mind
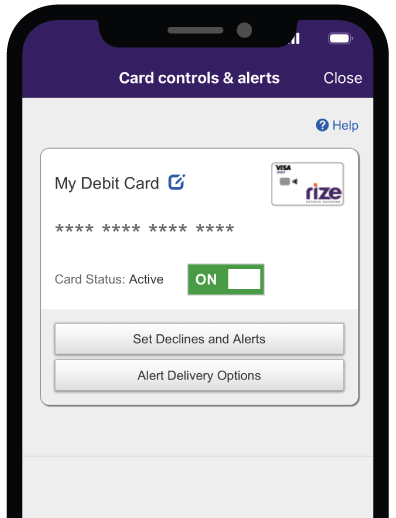
Get notified when spending hits your set amount or higher, so you can stay on top of your account in real time.
Set spending limits & alerts in card controls
Tap to add. Ready to use.
No more searching for your card – just tap with your phone when you’re ready to pay.
Add your card to yur mobile wallet in card management
Effective February 1, 2026
This EFT Disclosure & Agreement (Agreement), as amended from time to time, sets forth the terms and conditions governing the use of the Rize CU electronic transfer services. Disclosure information that applies to all electronic services offered by Rize CU is given below, followed by specific disclosure information for each service. Rize CU may also provide remittance transfers (defined by Regulation E, Subpart B, as an electronic transfer of funds of more than $15, which is requested by a sender and sent to a designated recipient in a foreign country by a remittance transfer provider). The terms and conditions for such electronic transfers will be disclosed to you separately when you receive those services and may differ from the terms and conditions disclosed herein. As applicable and to the extent not in conflict with such separately provided disclosures, the terms and conditions here will apply to remittance transfers that also meet the definition of an electronic fund transfer under Regulation E, subpart A. This agreement takes the place of all prior agreements and disclosures governing the use of all electronic services. By retaining, using, or allowing others to use the electronic services offered by Rize CU, you are agreeing to be bound by the terms and conditions of this agreement. In this agreement, the term “you” and “your(s)” refer to the member, and the terms “we,” “us,” and “our(s)” refer to Rize CU.
Personal identification number
The Credit Union will issue you a Personal Identification Number (PIN) that must be used with the ATM/Debit Card for transactions that require the use of a PIN. This number should be memorized. DO NOT write it on your debit card or where it is easily accessible by others. After memorizing your PIN, you should destroy the notice securely, without disclosing your PIN. If you forget, misplace, or otherwise disclose your PIN, contact the Credit Union, and we will issue you a new one.
Right to receive documentation of transactions
You will get a monthly account statement reflecting all of your transactions unless there is no activity in a particular month. In any case, you will get the statement at least quarterly. Depending on the terminal, or if the transaction is $15 or less, you may receive a receipt at the time you make a transaction at a terminal. If you do receive a receipt, you can keep the receipt to compare with your monthly statement from the Credit Union.
Your liability for lost, stolen, or unauthorized transactions involving Visa® debit card
Tell us AT ONCE if you believe your debit card and/or Personal Identification Number (PIN) has been lost or stolen, or if you believe an electronic transfer has been made without your permission using information from your check. Calling is the best way of keeping your possible losses down. You could lose all the money in your account (plus your maximum overdraft line of credit, if you have one with us). If you tell us within 60 days of our sending your statement, you can lose no more than $50 if someone used your debit card without your permission. If you DO NOT tell us within two (2) business days after you learn of the loss or theft of your debit card/PIN, and we can prove that we could have stopped someone from using your debit card or PIN without your permission if you had told us, your could lose as much as $500. If you do not tell us within 60 days after the statement was mailed to you, you may not get back any money you lost after the close of the 60 days and before notice to us. If your delay in notifying us was due to extenuating circumstances beyond your reasonable control, including extended travel, you or a member of your family’s serious illness or death, hospitalization, permanent mental impairment or serious physical impairment, unless the circumstance did not reasonably contribute to your delay in notifying us within the 60-day period, we will extend the 60-day period by a reasonable period.
Special Notice to Visa debit cardholders
If there is an unauthorized use of your Visa debit card or a Plus network or Interlink transaction, and the transaction takes place on the Visa network, then your liability will be $0. This provision limiting your liability does not apply to Visa corporate card transactions, Visa purchasing card transactions, anonymous Visa prepaid card transactions, ATM cash disbursements processed on non-Visa or non-Plus networks, or non-Visa PIN-less debit transactions. Additionally, your liability concerning unauthorized transactions may be greater than the above $0 liability limit, to the extent allowed under applicable law, if the Credit Union reasonably determines, based on substantial evidence, that you were negligent or fraudulent in the handling of your account or card. In any case, to minimize your potential liability, you should notify us of any unauthorized use no later than 60 days after your statement was mailed to you.
How to notify the Credit Union in the event of an unauthorized transaction
If you believe your debit card or PIN has been lost or stolen, or someone has transferred or may transfer money from your account without your permission, call 800.866.6474 or write to us at PO Box 8017, El Monte, CA 91734. You should also call the number or write the address listed above if you believe a transfer has been made using information from your check without your permission.
Business days
Our business days are Monday through Friday, excluding Saturday and holidays.
Our liability for failure to make transfers
If we do not complete a transaction to or from your savings or checking account on time or in the correct amount according to our agreement with you, we will be liable for your losses or damages. However, there are some exceptions. We will not be liable, for instance, if:
There may be other exceptions that are not specifically mentioned above.
In case of errors or questions about your electronic transfers
Llamada por teléfono 800.866.6474 or write to us at PO Box 8017, El Monte, CA 91734, as soon as you can if you think your statement or receipt is wrong or if you need more information about a transfer listed on the statement or receipt. We must hear from you no later than 60 days after we sent the first statement on which the problem or error appeared.
If you tell us orally, we may need you to send us your complaint or question in writing within 10 business days.
We will determine whether an error occurred within 10 business days after we hear from you and will correct any error promptly. If we need more time, however, we may take up to 45 days to investigate your complaint or question. If we decide to do this, we will credit your account within 10 business days for the amount you think is in error, so you will have the use of the money during the time it takes us to complete our investigation. (If the error you assert is an unauthorized Visa transaction, other than a cash disbursement at an ATM, we will credit your account within 5 business days unless we determine the circumstances or your account history warrant a delay, in which case you will receive credit within 10 business days.) If we ask you to put your complaint or question in writing and we do not receive it within 10 business days, we may not credit your account.
For errors involving new accounts, point-of-sale, or foreign-initiated transactions, we may take up to 90 days to investigate your complaint or question. For new accounts, we may take up to 20 business days to credit your account for the amount you think is in error.
We will tell you the results within three business days after completing our investigation. If we decide there was no error, we will send you a written explanation within three business days after we finish our investigation. You may ask for copies of the documents we used in our investigation.
Charges
In order to obtain the electronic services listed, you must open and maintain a savings or checking account. All charges associated with our electronic fund transactions are disclosed within our Schedule of Fees & Charges.
Disclosure of account information to third parties
We will disclose information to third parties about your account or the transfers you make:
Address change
Keep the Credit Union informed of your current address to ensure correct mailing of monthly statements. If we do not have your current address on file, you will be assessed the fee as stated within our Schedule of Fees & Charges. If you have elected to receive statements electronically, it is also your responsibility to keep the Credit Union informed of your current email address.
Amendments
The Credit Union may change the terms and conditions of this agreement from time to time by mailing written notice to your address as it appears on our records. If any change results in greater cost or liability to you or decreases access to your accounts, you will be given at least 21 days prior notice of the change. Prior notice may not be given where an immediate change in terms or conditions is necessary to maintain the integrity of the system and/or the security of debit cards or designated accounts.
Termination
You may terminate this agreement with us at any time. The Credit Union reserves the right to terminate this agreement and/or your use of your debit card or PIN with or without cause. We may do so immediately if:
Additional benefits/card enhancements
The Credit Union may, from time to time, offer additional services to your account. Some may be at no additional cost to you, and others may involve a specified fee. You understand the Credit Union is not obligated to offer such services and may withdraw or change them at any time.
Waiver of rights
The Credit Union can delay enforcing any of the provisions under this agreement or the law any number of times without losing its right to enforce them at a later date.
Other agreements
Except as stated otherwise in the agreement, this agreement does not alter or amend any of the terms or conditions of any other agreement you may have with the Credit Union.
Severability
If any part of this agreement should be held to be unenforceable, the remaining provisions of this agreement shall remain in full force and effect.
Who is bound by this Agreement?
Each person who signs the application agrees to be bound by the terms and conditions of this agreement. If more than one person signs the application, all signers are jointly and severally liable. The Credit Union can waive or delay the enforcement of its rights to one signer without affecting its ability to enforce its rights to the other signers. The agreement is also binding upon your heirs, personal representatives, and successors.
Signatures
By using your access to the system, or authorizing anyone else to use your access to the system, and/or by signing the application, you agree to be bound by the terms and conditions of this Agreement & Disclosure.
Effective February 1, 2026
Issuance of card
Card means the Rize CU Visa debit card and any duplicates, renewals or substitutions the Credit Union issue to you; Account means the account designated on the application for your debit card.
Responsibility for transactions
You are responsible for all transactions you make with the Card or that you authorize another person to make with the Card. You understand that if you disclose your Visa Debit card PIN to anyone, they will have access to all accounts identified by your account number. If the Account is a joint account, all transactions involving the account are binding on all accountholders.
Merchant disputes
For POS transactions directly accessing a line of credit, the Credit Union is not responsible for the refusal of any merchant or financial institution to honor the card. The Credit Union is subject to claims and defenses (other than tort claims) arising out of goods or services you purchase with the card if you have made a good faith attempt but have been unable to obtain satisfaction from the merchant or service provider and
Limitations on dollar amounts and frequency of transactions
Purchases made above the floor limit of the merchant will require an authorization number from Visa.
Visa debit card default limit is up to $3,000 ($250 for Teen Checking accounts) for every 24-hour period when used at places that accept Visa debit cards as long as your available balance will cover the transaction or have not been assigned a custom limit. You may make up to 15 total transactions per each 24-hour period.
Use of the card
You may use the Card and PIN to:
You may use the Card without the PIN to:
Some of these services may not be available at all terminals. Use of the Card, the Account number on the Card, the PIN or any combination of the three for payments, purchases, or to obtain cash from merchants, financial institutions or others who honor Visa debit cards is an order by you for the withdrawal of the amount of the transaction from your Account. Each transaction with the Card will be charged to your Account on the date the transaction is posted to your Account. When the Credit Union receives notification of a debit card transaction, it will put a hold on an equivalent amount of funds in your checking account for 3 days or until the day the transaction is charged to your account.
All card transactions covered by this Agreement are subject to the terms and conditions of your Account agreements with us governing the affected Accounts, except as modified by this Agreement. Any future changes to your Account agreements may affect the use of the card.
Illegal use of Visa® debit card
You agree that your Visa debit card Account will not be used to make or facilitate any transaction(s) that are or might be construed to be illegal pursuant to applicable law, rule or ordinance, including but not limited to gambling. Said use, including any such authorized use, will constitute an event of default under this Agreement. You agree that the Credit Union has no liability, responsibility or culpability whatsoever for any such use by you or any authorized user(s). You agree that you are responsible for repayment of any and all debts incurred for these transactions. You further agree to indemnify and hold the Credit Union harmless from any suits, liability, damages or adverse action of any kind that results directly or indirectly from such illegal use.
Overdrafts
You promise to pay the Credit Union immediately upon demand for any negative (overdraft) balance arising in your Account, unless you have available overdraft privileges such as Courtesy Pay. If you do not have overdraft privileges, the Credit Union may deduct the amount of any overdraft on your Account from any other account you have with the Credit Union, except an Individual Retirement Account.
Refusal to honor card
The Credit Union is not liable for the refusal or inability of any electronic terminal to honor the Card or to complete a withdrawal from your Account, or for their retention of the Card. The Credit Union is also not responsible for the refusal of any merchant or financial institution to honor
the Card or for their retention of the Card.
Transacción del extranjero
Purchases and cash advances made in foreign currencies will be billed to you in US dollars. Transactions processed outside of the United States, or in a foreign currency may be charged a foreign transaction fee, regardless of whether there is a currency conversion associated with the transaction. Foreign transactions include transactions initiated in the US authorizing access to a debit card, credit card or deposit account number using a telephone, computer or mobile device application but with a merchant who processes the transaction in a foreign country. The conversion rate in dollars will be a rate selected by Visa from a range of rates available in wholesale currency markets for the applicable central processing date, which rate may vary from the rate Visa itself receives, or the government-mandated rate in effect for the applicable central processing date in each instance, plus a one percentage point (1%) fee
charged by the Issuer.
Consumer reports
The Credit Union makes credit available to its members on a regular basis. The applicant(s)/accountholder(s) of the account authorizes the Credit Union to obtain consumer reports in connection with credit and business transactions involving the applicant(s)/accountholder(s), including but not limited to applying for membership, the opening of a savings or checking account or the issuance of an debit card, or other service provided by the Credit Union, and the applicant(s)/accountholder(s)of the account authorize any person, association, or corporation to furnish on request of this Credit Union, information concerning the affairs of the applicant(s)/accountholder(s). The applicant(s)/accountholder(s) also authorizes the Credit Union to furnish
information concerning the account to consumer reporting agencies.


Administración del dinero Money Management
SEGUIMIENTO, PRESUPUESTACIÓN Y GESTIONE TODAS SUS CUENTAS


